
By James L. C. Meyers, Broker & REALTOR®, Block City Homes
On Veterans Day, we take time to recognize the men and women who have served our country, as well as the families who have stood alongside them. Their sacrifices deserve our gratitude every day of the year.
In my work as a Realtor, one way I get to see that appreciation translate into something tangible is through the VA home loan program.
After nearly 20 years in real estate, I've worked with buyers using a variety of financing options. One benefit I believe more eligible veterans and active-duty service members should understand is the opportunity to purchase a home using a VA loan.
What Makes a VA Home Loan Different?
The VA home loan program was designed to help eligible veterans, active-duty service members, and certain surviving spouses achieve homeownership. It offers several advantages that can make a meaningful difference when purchasing a home.
Some of the most notable benefits include:
No down payment required: Qualified buyers can often finance 100% of the home's purchase price, provided the property appraises appropriately and the buyer meets lender requirements.
No monthly private mortgage insurance (PMI): Unlike many conventional loans with smaller down payments, VA loans do not require monthly PMI.
Competitive interest rates: VA loans often offer favorable interest rates compared with other financing options.
Flexible credit requirements: VA loans can offer more flexibility than some conventional financing programs, although individual lenders establish their own qualification requirements.
There may also be a VA funding fee, depending on the borrower's circumstances, though some veterans are exempt.
Why This Matters in the Chattanooga Housing Market
Here in the Chattanooga area, having the right financing in place can make a significant difference in a buyer's homeownership journey.
One of the biggest misconceptions I encounter is that buyers need to have a substantial down payment saved before they can begin looking for a home. For eligible veterans and service members, that simply may not be the case.
A VA loan can help preserve savings, reduce upfront costs, and give buyers more flexibility when deciding what they can comfortably afford.
That doesn't mean every VA loan is automatically the best option for every buyer. Your income, credit, financial goals, and the type of property you're considering all matter. Understanding how the different financing options compare is an important part of making a good decision.
Don't Overlook a Benefit You've Earned
If you're a veteran or active-duty service member who hasn't explored your VA home loan benefits, I encourage you to take a closer look before assuming homeownership is out of reach.
You don't necessarily need to wait until you've saved for a conventional down payment to start exploring your options.
I'd be glad to help you understand the local housing market, walk through the home-buying process, and connect you with a lender experienced in VA financing.
And today, especially, thank you for your service. My dad is a veteran, and it’s always an honor to help those who have served our country find a place to call home.
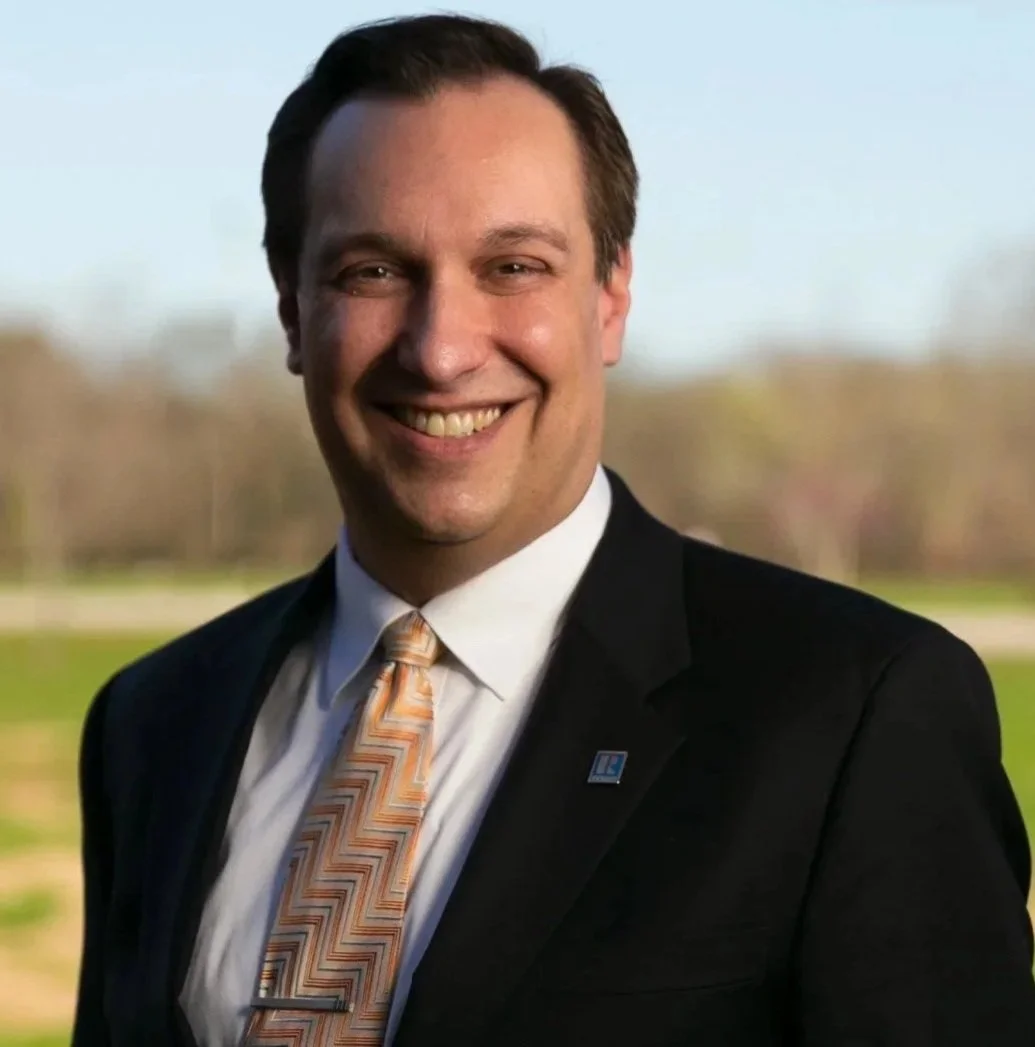
James L. C. Meyers is a second-generation broker and owner of Block City Homes who helps families buy and sell with confidence through every stage of homeownership across Greater Chattanooga, Northwest Georgia, and Northeast Alabama.
